
Guides
How to Read a Loan Estimate: A Page-by-Page Guide
The Loan Estimate is a three-page standardized form that lets you compare lenders. Learn what each section means and what to check before you choose.
By Muhammad Bashir, founder of TotalMonthlyPublished · 4 min read
When you apply for a mortgage, the lender must give you a Loan Estimate within three business days. It is a standardized three-page form, so estimates from different lenders look the same and can be compared line by line. Getting several and comparing them is one of the most effective ways to save money.
Page 1: the summary
Loan terms. The loan amount, interest rate, monthly principal and interest, and whether any of them can change. It also shows whether there is a prepayment penalty or a balloon payment. Check that the rate and loan type match what you discussed.
Projected payments. The estimated total monthly payment, including principal and interest, mortgage insurance, and estimated escrow for taxes and insurance. It shows how the payment may change over time, which matters for adjustable-rate loans.
Costs at closing. An estimate of the total closing costs and of the cash to close, which includes your down payment. This is the number to compare with your savings.
Page 2: the details of closing costs
This page itemizes the costs in labeled sections:
- A. Origination charges. The lender’s own fees, including any points. This is where lenders differ the most.
- B. Services you cannot shop for. Items the lender selects, such as the appraisal and credit report.
- C. Services you can shop for. Things like title services, where you can choose your own provider.
- D. Total loan costs. The sum of A, B and C.
- E to H. Other costs. Taxes and fees on the deed, prepaid items such as homeowners insurance and interest, and the initial escrow deposit.
- I and J. Totals. The total other costs, and the total closing costs, minus any lender credits.
Page 3: comparisons and other considerations
The Comparisons box helps you see the total cost of a loan:
- In 5 years: the total you would have paid in principal, interest, mortgage insurance and loan costs after five years, and how much principal you would have paid off.
- APR: the annual percentage rate, which folds in some of the loan costs. Use it to compare offers with different points and fees. See the APR calculator.
- TIP (total interest percentage): total interest over the loan as a percentage of the loan amount.
The page also lists other considerations, such as whether the loan is assumable, whether a late payment fee applies, and whether the servicer may transfer your loan.
How to compare estimates
- Ask each lender for a Loan Estimate for the same loan amount, type and term, on the same day.
- Compare Section A (origination) and the total closing costs first, since lenders control those.
- Compare the rate and APR together. A low rate with high costs can have a higher APR.
- Compare cash to close and the monthly payment against your budget.
- If you will not keep the loan long, use the five-year comparison rather than the APR.
A worked example: comparing two estimates
Say two lenders quote a $315,000, 30-year fixed loan on the same day.
| Lender A | Lender B | |
|---|---|---|
| Interest rate | 6.5% | 6.25% |
| Points | None | 1 point ($3,150) |
| Other origination fees | $4,000 | $1,500 |
| Section A total | $4,000 | $4,650 |
| Monthly principal and interest | $1,991.01 | $1,939.51 |
| APR (approximate) | 6.62% | 6.39% |
| Paid in 5 years, counting only these charges | $123,461 | $121,021 |
| Principal paid off in 5 years | $20,125 | $20,988 |
Lender B costs $650 more at closing but saves $51.50 a month, so it pays back the difference in about 13 months. If you expect to keep the loan longer than that, Lender B is cheaper. The APR and the five-year comparison both point the same way.
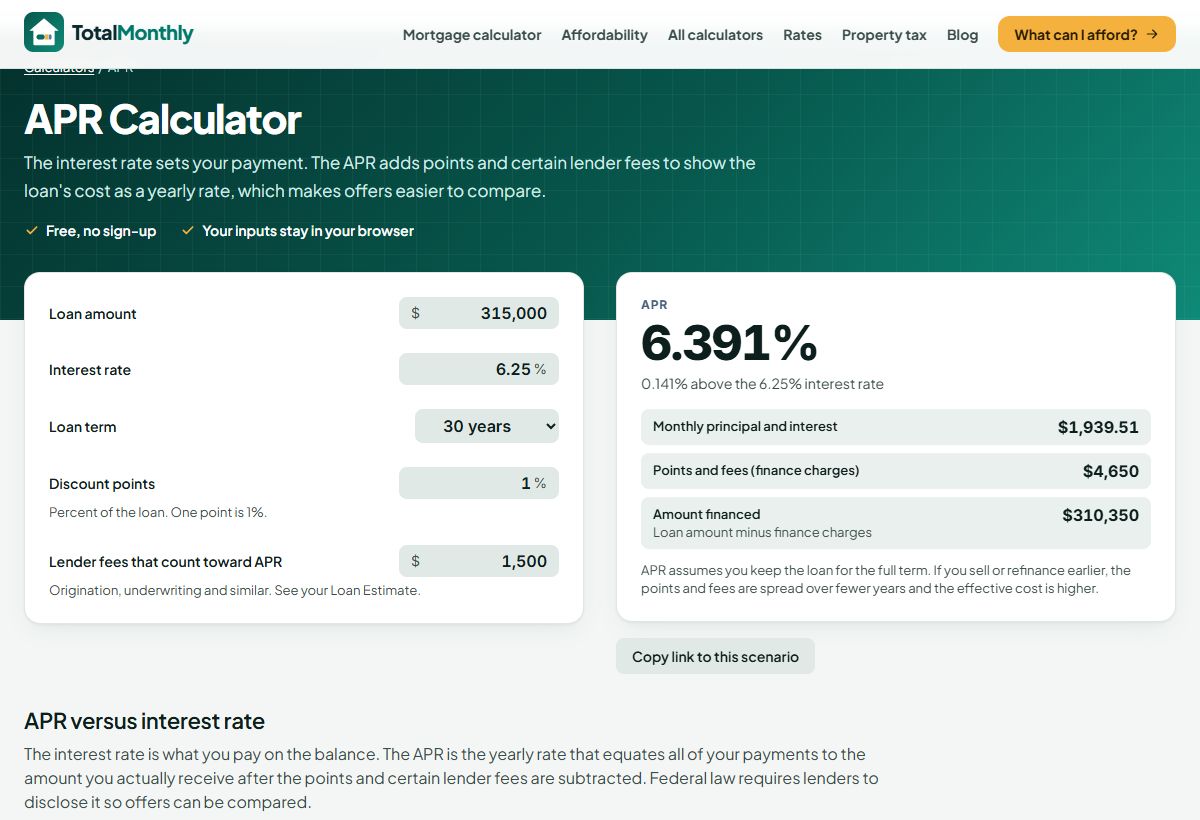
Lender B’s offer in the APR calculator.
The APR here treats every origination charge as a finance charge, a simplification. Compare the full forms line by line.
Use it to negotiate
Lenders will sometimes match a competitor’s fees if you show them a lower estimate. You can also ask them to explain or waive items you do not understand. Before you close, compare the final Closing Disclosure, which you should receive at least three business days before closing, with your Loan Estimate and ask about any large differences.
Estimates are not commitments
A Loan Estimate is an estimate, and its rate may not be locked. Ask whether the rate is locked, for how long, and what the lock costs. Learn more about the costs in the closing costs guide, and try the numbers in the mortgage calculator.
Common questions
How long is a Loan Estimate good for?
For a limited time, often around ten business days; the form states the period. The rate isn’t locked unless you lock it.
Can the lender change the numbers after I apply?
Some fees are not allowed to increase, others can increase within a limit, and some can change freely if you choose the service provider. Changes in your circumstances or the loan can also trigger a revised estimate. Compare the Closing Disclosure you receive before closing with your estimate.
Do I have to choose the lender who gave me the estimate?
No. Receiving a Loan Estimate does not commit you to the lender. Getting several and comparing them is the point, and requesting multiple mortgage estimates within a short window is usually treated as a single inquiry for credit scoring purposes.
Key takeaways
- Compare Loan Estimates for the same loan from several lenders, on the same day.
- Focus on origination charges, total closing costs, cash to close, the rate and the APR.
- Review the Closing Disclosure against the estimate before you sign.
For education, not financial or legal advice. Rules, rates and fees change; confirm with a lender or licensed professional. See our methodology and disclaimer.
Keep reading
All guides
Guides
Pay Off Your Mortgage Early or Invest? A Worked Comparison
Extra mortgage payments give a guaranteed return equal to your loan rate. Investing might earn more or less. See a worked example and the break-even return.
Guides
How Mortgage Interest Is Calculated, with an Example
How a mortgage's interest is worked out each month, the total over the loan, daily interest, and add-on vs simple interest, with a $400,000 example.
Costs
Florida Amendment 3 Passed: What It Means for Buyers
Florida Amendment 3 passed. The homestead exemption for non-school taxes rises to $150,000 in 2027 and $250,000 in 2028. See the math on a $400,000 home.