
Buying
First-Time Homebuyer Costs: Everything Beyond the Down Payment
A timeline of the costs of buying a home, from earnest money and inspections to closing, moving and ongoing maintenance, so your budget covers more than the price.
By Muhammad Bashir, founder of TotalMonthlyPublished · 4 min read
The down payment gets most of the attention, but it is only one part of what a first home costs. Plan for the whole timeline so you do not run out of cash right after you get the keys.
Before you make an offer
- Pre-approval costs. A credit check may carry a small fee. Pre-approval tells you what a lender will offer and makes your offer stronger.
- Saving for the down payment. Lower down payments are possible, but they raise your monthly cost. See the down payment calculator.
When you make the offer
- Earnest money deposit. A good-faith deposit held in escrow, commonly a percentage of the price that varies by market. It is credited toward your down payment or closing costs at closing, and it can be at risk if you back out of the contract without a permitted reason.
During the contract period
- Home inspection. Typically a few hundred dollars. A thorough inspection can save you far more by revealing problems before you are committed. Specialty inspections such as sewer, radon or termites may cost extra.
- Appraisal. The lender orders it and you usually pay for it.
- Other fees. Application or credit fees, depending on the lender.
At closing
- Your down payment.
- Closing costs, commonly about 2% to 5% of the price: lender fees, title and settlement services, recording fees, and prepaid items such as insurance and property taxes. Read the closing costs guide.
- Discount points, if you buy down the rate. See mortgage points.
Right after you move in
- Moving costs. Movers or truck rental, deposits for utilities, and cleaning.
- Immediate repairs and updates. Even a well-inspected home has surprises. Many buyers set aside money for these.
- Furniture, appliances and tools. Items that renters often did not need to buy.
Ongoing costs every month and every year
- Principal and interest.
- Property tax and homeowners insurance, often paid through escrow. See property taxes when you buy.
- Mortgage insurance, if you put less than 20% down. See PMI explained.
- HOA or condo fees, if applicable.
- Utilities, which may be higher than in an apartment.
- Maintenance and repairs. A common rule of thumb is around 1% of the home’s value each year, more for older homes.
A worked example
Here is how the costs add up for a $350,000 home bought with 10% down and a 30-year loan at 6.5%. The closing cost, inspection, insurance and PMI figures are estimates, so replace them with your own quotes.
Cash you need by move-in:
| Item | Amount |
|---|---|
| Down payment (10%) | $35,000 |
| Closing costs (about 3%) | $10,500 |
| Inspection and appraisal | $1,000 |
| Moving | $1,500 |
| First-year repair fund (1% of price) | $3,500 |
| Total | $51,500 |
Your earnest money is part of the down payment or closing costs, not an extra cost. The total does not include your separate emergency fund.
Monthly cost after you move in:
| Item | Amount |
|---|---|
| Principal and interest on $315,000 | $1,991 |
| Property tax (about 1% a year) | $292 |
| Homeowners insurance | $165 |
| PMI (estimated 0.7% a year) | $184 |
| Maintenance fund (1% a year) | $292 |
| Total | $2,924 |
The mortgage payment alone is under $2,000, but the real monthly cost is close to $2,900 before utilities and any HOA fee. Budget from the larger number.
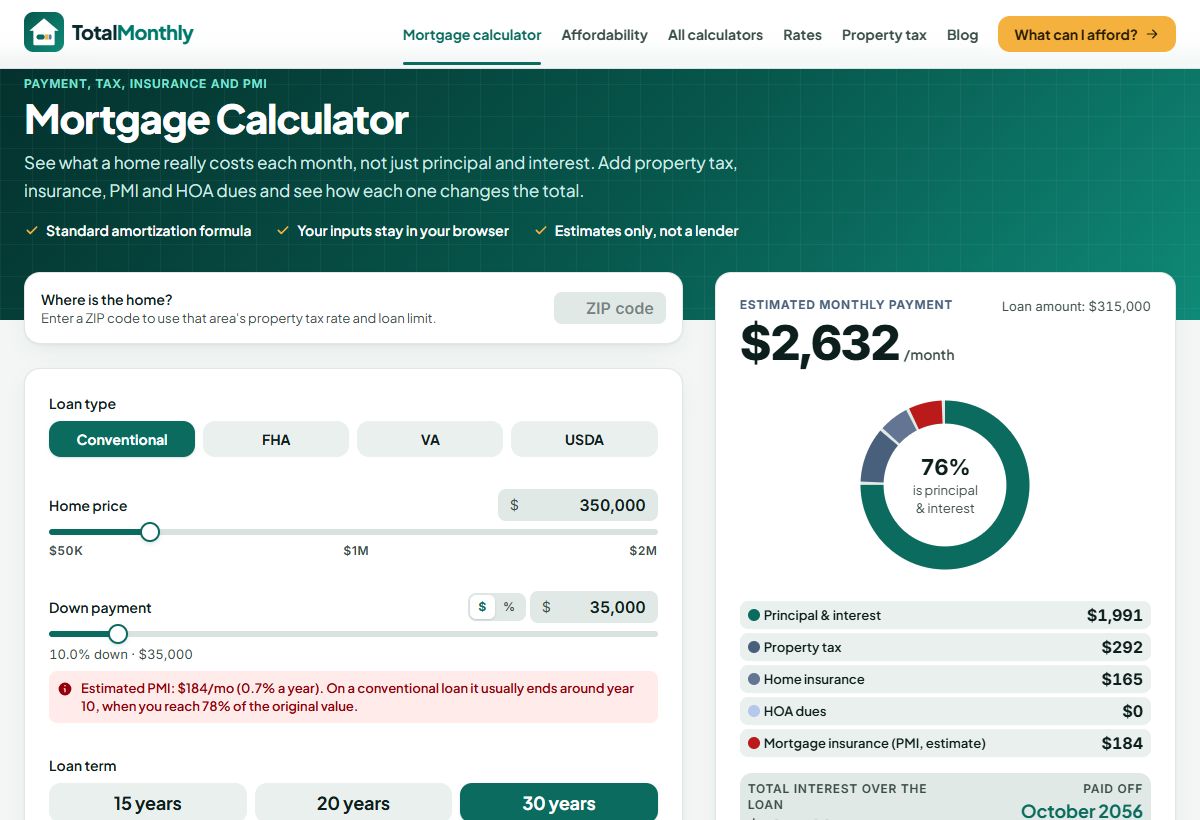
The same home in the mortgage calculator: $2,632 a month before setting aside money for maintenance.
A simple budget
| When | What to plan for |
|---|---|
| Before offer | Down payment savings, emergency fund |
| Offer | Earnest money |
| Contract | Inspection, appraisal |
| Closing | Down payment, closing costs |
| Move-in | Moving, repairs, essentials |
| Each month | Payment with taxes and insurance, utilities, maintenance fund |
Keep a cushion
Lenders often look for reserves after closing, and so should you. A roof or a furnace can cost thousands. Keep an emergency fund separate from your down payment.
Use the affordability calculator to find a price whose full monthly payment fits your income, then subtract closing costs and reserves from your savings to decide the down payment.
Common questions
How much should I have saved before I start looking?
Enough for your down payment, closing costs and a cushion for moving and repairs, plus your regular emergency fund. A useful test: after paying everything at closing, would you still have several months of expenses in savings? If not, aim to save more or look at a lower price.
Are there programs that help with the down payment?
Many state and local housing agencies offer down payment assistance or special loans for first-time or moderate-income buyers, and some employers and nonprofits do as well. Some have income limits or must be repaid. A HUD-approved housing counselor can help.
Should I use all my savings on the down payment?
Usually not. A larger down payment lowers your payment and may avoid mortgage insurance, but leaving yourself with no reserves is risky when the first big repair arrives. Balance the two.
Key takeaways
- Budget for the whole timeline: earnest money, inspections, closing, moving, repairs and ongoing costs.
- Keep an emergency fund separate from your down payment.
- Use the affordability calculator to size the monthly payment, then work backward to the savings you need.
For education, not financial or legal advice. Rules, rates and fees change; confirm with a lender or licensed professional. See our methodology and disclaimer.
Keep reading
All guides
Buying
How Much House Can I Afford? A Practical Guide
Start from income and debts, not listing prices. Learn the 28/36 guideline, what counts in the payment, and how down payment, taxes and reserves change the answer.
Buying
Rent vs Buy: How to Think About the Decision
Buying beats renting only in some situations. Learn the costs on each side, why time horizon matters most, and how to test your own assumptions.
Costs
Florida Amendment 3 Passed: What It Means for Buyers
Florida Amendment 3 passed. The homestead exemption for non-school taxes rises to $150,000 in 2027 and $250,000 in 2028. See the math on a $400,000 home.